If you mapped your financial life on a graph, the picture might be simpler than you expect.
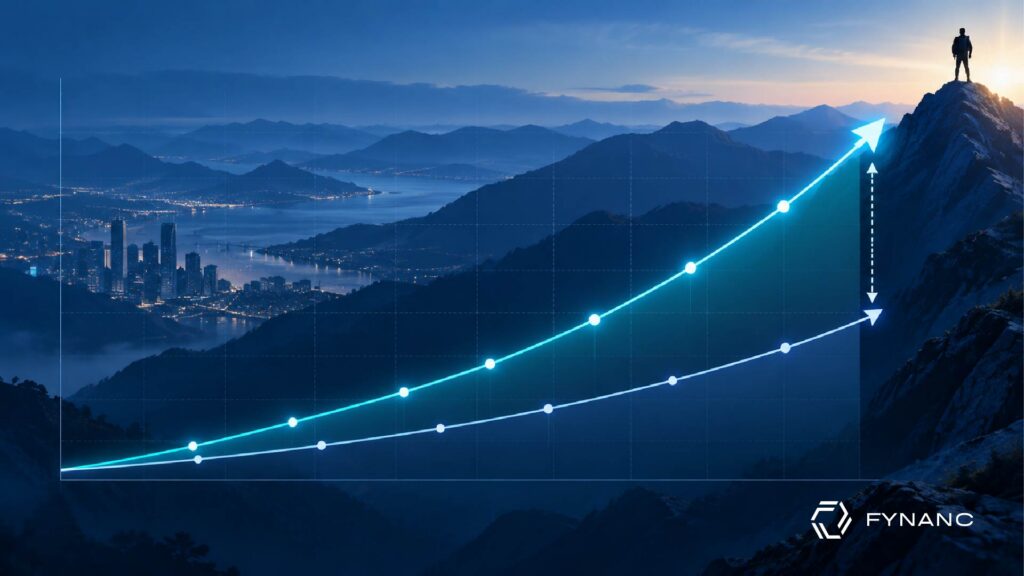
You would see two lines: your Freedom Line and your Journey Line.
The relationship between these two lines can help explain why some people make steady financial progress while others spend decades working, saving, and investing without ever feeling significantly closer to financial freedom.
The Two Lines
The Freedom Line represents the amount of capital and passive cash flow required to support your ideal lifestyle without relying on earned income.
It is your financial target.
The Journey Line represents where you are today—the capital you have accumulated and how it is currently structured.
In theory, the objective is straightforward: grow your Journey Line until it intersects your Freedom Line.
The challenge is that both lines are moving.
A Race of Unequal Speed
While you are working to grow your Journey Line, your Freedom Line may also continue rising.
Inflation, lifestyle changes, family responsibilities, and the increasing cost of living can all push the target higher.
At the same time, a traditional wealth-building strategy may cause the Journey Line to move relatively slowly through fixed savings contributions and long-term passive investment growth.
The result can be a widening gap between where you are and where you need to be.
The diagram in the original article illustrates this clearly: the Freedom Line rises while the more slowly moving Journey Line struggles to close the distance.
Why This Is a Structural Problem
When people feel they are falling behind financially, the instinct is often to blame discipline.
They assume they need to save more, spend less, or work harder.
But the problem may instead lie in the structure of the strategy.
Traditional wealth-building approaches commonly rely on:
- Fixed contributions from active income
- Passive compounding in market-based investments
- Very long investment timelines
When the capital base is still relatively small, passive compounding may not create enough movement to materially change the trajectory.
The Illusion of Progress
This can create a frustrating situation.
You may be consistently saving, contributing to retirement accounts, and following conventional financial advice while the distance between your Journey Line and Freedom Line continues to grow.
Your balance may be increasing, but that does not automatically mean you are closing the gap quickly enough.
The more useful question becomes:
How fast is your financial position changing relative to your target?
The Real Shift: Bending the Line
Instead of simply trying to push the Journey Line upward a little faster, the objective is to change its trajectory.
That means introducing strategies capable of creating more non-linear financial movement.
This can include:
Strategic Leverage
Strategic Leverage
Using financial structures that allow capital to work more efficiently.
Access to Capital
Maintaining liquidity and optionality so capital remains available when opportunities arise.
Velocity of Deployment
Moving capital through structures designed to create financial capacity rather than automatically locking it away for decades.
The emphasis shifts from simply asking how long wealth building will take to asking how the rate of change can be accelerated.
The Gap Is Information
The distance between your Journey Line and Freedom Line is not simply a sign that you have failed.
It is information.
That gap can help reveal whether your current financial strategy is capable of reaching your target within the timeframe that matters to you.
Instead of functioning purely as a financial “Technician” who manages accounts and individual investments, the objective is to think more like a Strategist who designs the financial system itself.